Forward points and the cross-currency basis
Distinguish a forward exchange rate from a forecast and identify the funding assumptions behind parity.
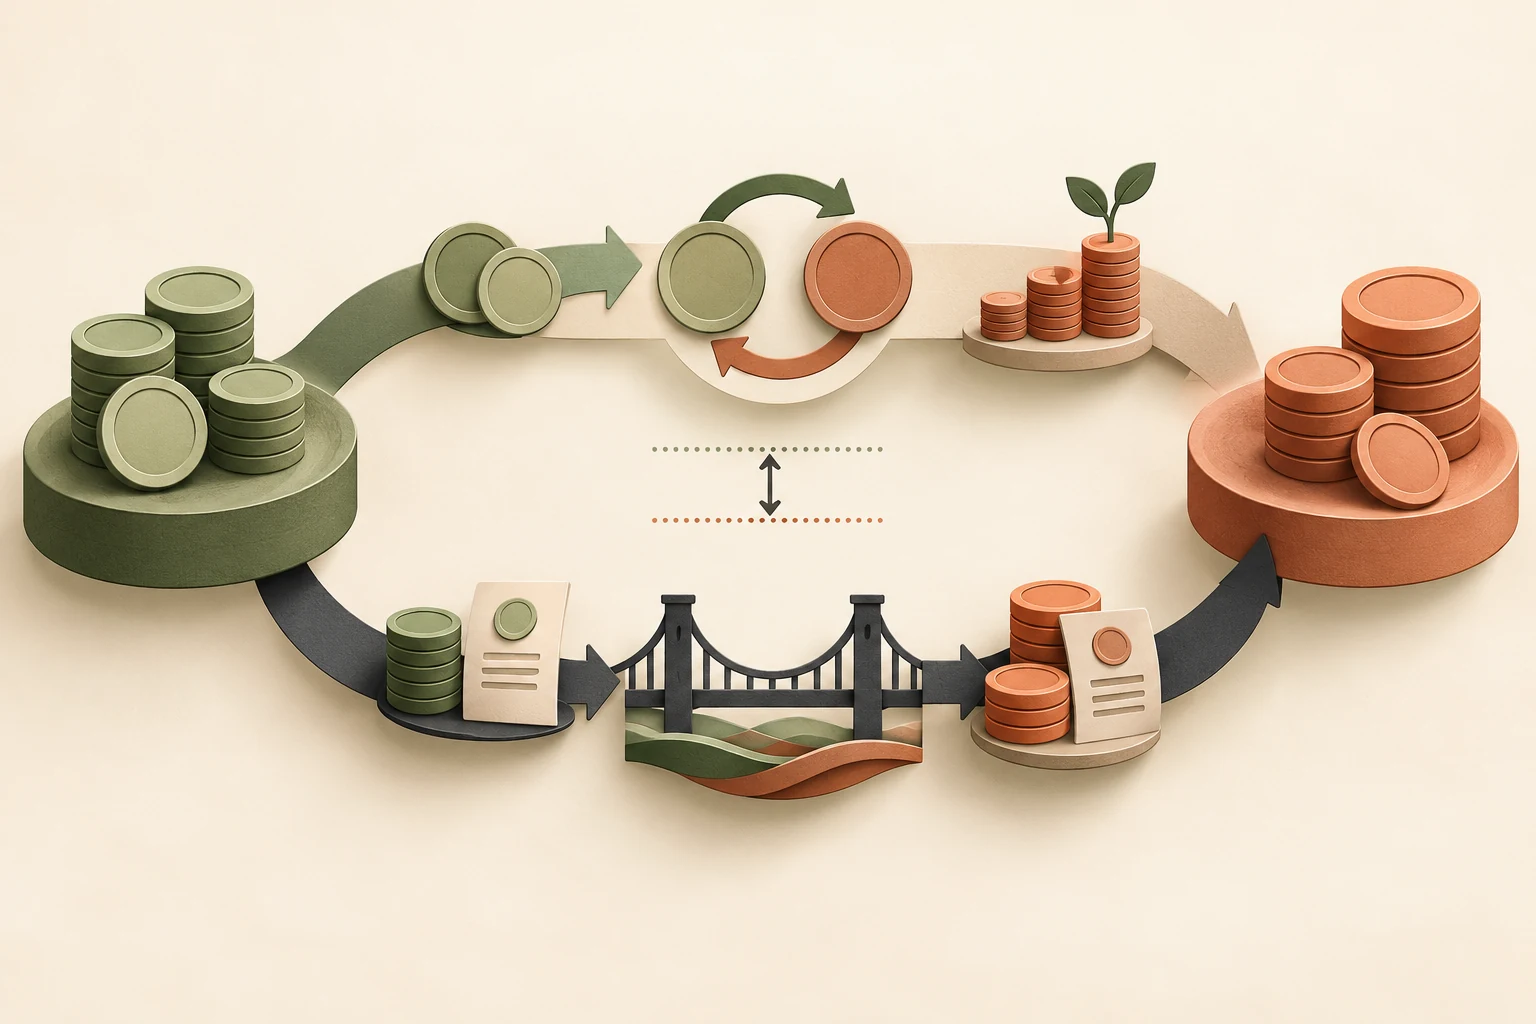
A future transaction price, not a prediction
A currency forward specifies an exchange rate for a future exchange under agreed contract terms. Its price is linked to spot and the relative financing costs of the two currencies. A forward above today's spot therefore does not automatically mean dealers expect the base currency to appreciate. Confusing a financing relationship with a forecast leads to misleading carry narratives.
Under a simplified one-period framework, if S is dollars per euro, the forward is S multiplied by one plus the dollar interest rate, divided by one plus the euro interest rate. This assumes comparable borrowing and lending terms and ignores market frictions. The units and time period must be consistent; annual rates cannot be inserted unchanged into a three-month calculation.
With simple annualized rates and a common year fraction T, write the benchmark as F = S × (1 + rUSD × T) ÷ (1 + rEUR × T). At spot 1.10, dollar funding of 5%, euro funding of 3% and T = 0.25, the illustrative forward is about 1.10546, or about 54.6 pips above spot. Real calculations must use each currency's actual day-count and funding convention. The positive points arise here from relative financing, not from adding a bullish forecast.
Reconstruct the economic comparison
Consider two ways to deliver dollars after one year: invest dollars directly, or convert dollars into euros, invest the euros and lock their future conversion back to dollars. Covered interest parity describes the forward relationship that equalizes those routes under its assumptions. The currency risk in the second route is covered by the forward rather than left open.
Real institutions cannot necessarily borrow and lend unlimited amounts at the same rate. Credit limits, collateral, capital requirements and balance-sheet costs all affect implementation. An apparent difference in a spreadsheet is not a free profit unless every required leg can actually be executed at the assumed size and terms.
To see the equality directly, start with one dollar. The domestic route ends with 1 + rUSD × T dollars. The foreign route buys 1/S euros, earns the euro rate, then sells the resulting euros at F, giving F × (1 + rEUR × T) ÷ S dollars. Setting those terminal amounts equal produces the formula. Remove the forward conversion and the equality no longer locks the outcome: the unknown future spot rate replaces F, reopening exchange-rate risk.
Understand the basis as a price of constraints
Observed forward and swap pricing can depart from the simplest parity calculation. The cross-currency basis summarizes a related funding adjustment under specified market conventions. Demand for hedging, dollar funding needs and constraints on intermediaries can keep that adjustment from vanishing immediately. A nonzero basis is a reason to inspect the financing assumptions, not to declare that markets have forgotten arithmetic.
Sign conventions differ with the currency pair and which leg receives the spread. Never infer expensive or cheap funding from a bare negative number without reading the convention. Record the reference rates, maturity, collateral framework and quotation direction. Comparing two basis series with different definitions can create a false change or a false opportunity.
An observed forward premium does not by itself establish a basis. Most of that premium may be the ordinary interest-rate differential. First calculate the comparable parity benchmark; only then examine the residual with the correct spread convention. Comparing a secured short-term dollar rate with an unsecured foreign rate can manufacture an apparent anomaly because the instruments have different credit and collateral characteristics. A useful basis calculation matches maturity and risk assumptions, not just currency labels.
Keep carry and spot risk separate
An investor who leaves the eventual conversion unhedged is taking exchange-rate risk. A higher interest rate can be more than offset by depreciation. An investor who hedges conversion through a forward generally pays or receives forward points that reflect much of the interest differential, with basis and costs adding further detail. The two strategies are economically different.
A strategy report should separate spot movement, financing accrual, forward valuation and transaction costs. Simply adding a policy-rate differential to a spot return may double count or mismeasure the financing actually charged by a broker. Rolling retail products, forwards and futures use different mechanisms. Use the instrument's cash flows rather than a convenient macroeconomic proxy.
The price of a new forward is different from the value of an existing forward. A contract entered yesterday at K can become valuable when today's comparable forward F changes. For a euro buyer, a simplified dollar value is the euro notional multiplied by F − K, discounted to today using the appropriate dollar curve. If F falls below K, the position has negative value even though no principal may yet have changed hands. Collateral terms can turn that mark-to-market change into an immediate cash demand.
Stress the roll and the counterparty
A one-year investment hedged with successive one-month forwards has future roll-price uncertainty. The initial one-month quote cannot guarantee the cost of the following eleven months. A longer contract reduces that particular uncertainty but may change credit exposure, collateral needs and flexibility. The appropriate comparison is the complete sequence of obligations.
For research, build a table with spot, both funding curves, forward points and all-in costs at matching timestamps. Mark assumptions that cannot be observed directly. Then test a funding-spread increase alongside an adverse spot move and tighter collateral requirements. The combined scenario shows why a mathematically modest basis can become important when large notionals or repeated refinancing are involved.
Check the model with an equal-rate case: if both currencies accumulate at the same rate under identical assumptions, the calculated forward equals spot. Then change only one rate and explain the resulting direction in words. These boundary checks help catch reversed ratios before a more complicated funding curve conceals the mistake.
Keep liquidity and credit stresses separate in the model. A profitable forward can leave a claim on a counterparty, while a losing forward can require cash or eligible collateral before the underlying asset is sold. Both conditions can occur across different contracts in the same portfolio. Netting only the final gains and losses assumes enforceable offsets, matching settlement dates and usable cash. Those assumptions must be checked rather than inferred from a small net number.