Foreign-exchange intervention: mechanism, signals and limits
Analyze what an intervention changes without treating central-bank activity as a guaranteed price floor.
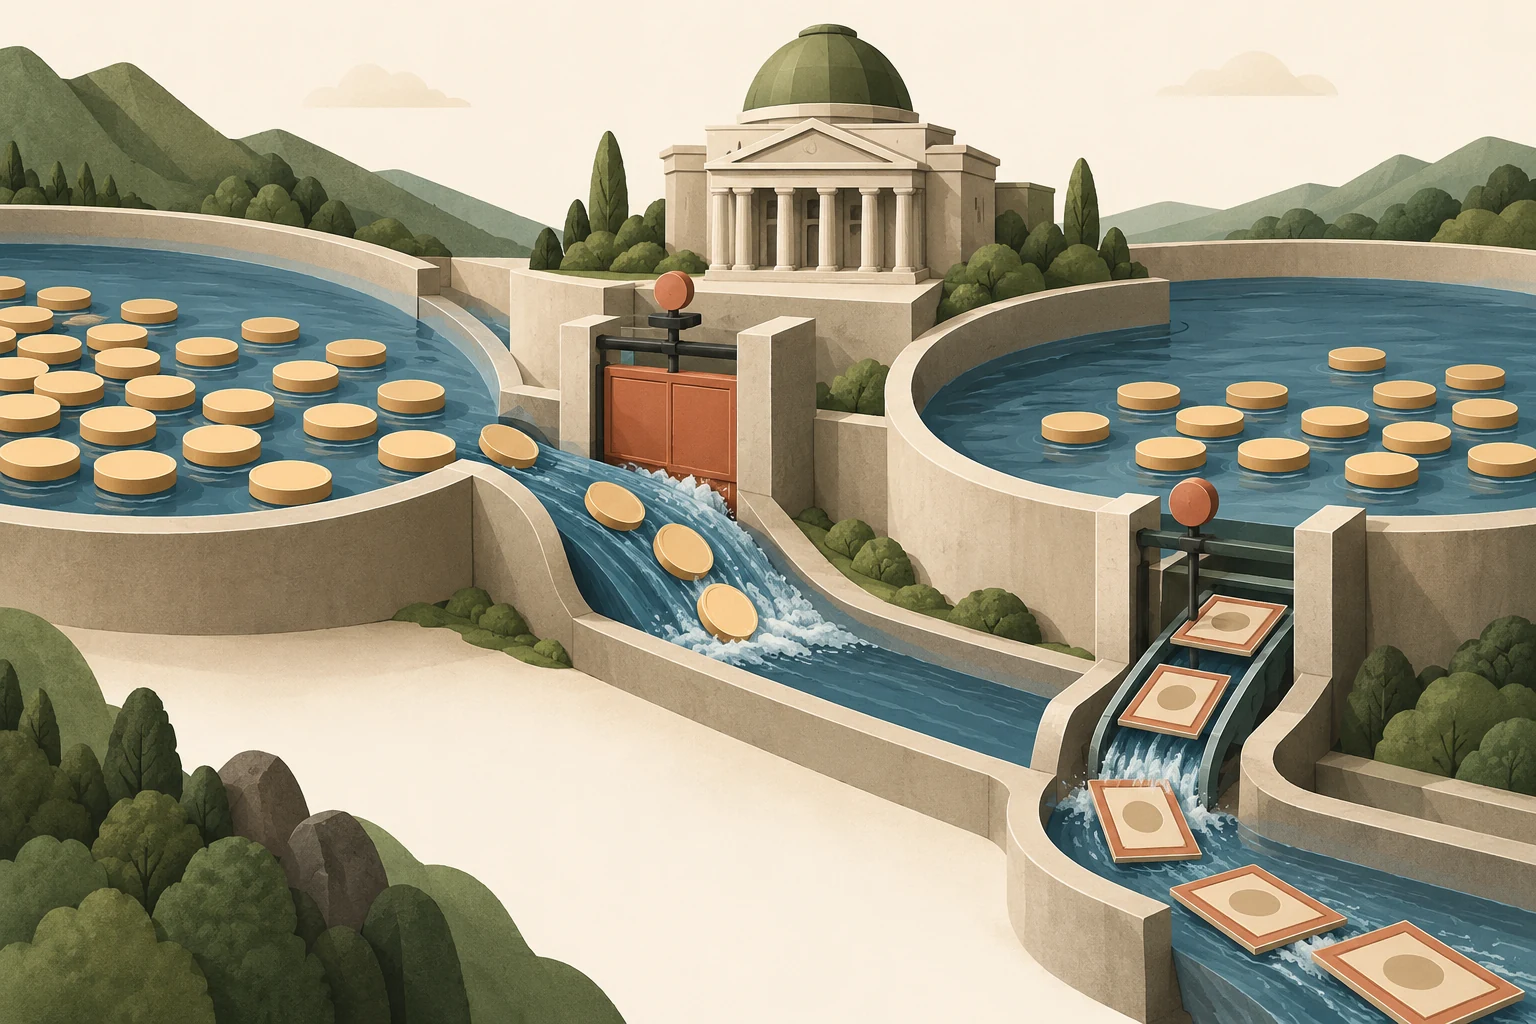
Describe the actual operation
Foreign-exchange intervention involves official transactions intended to influence currency-market conditions or the exchange rate. Buying foreign currency while selling domestic currency changes the assets and liabilities involved; selling reserves to buy domestic currency reverses that direction. An announcement, an actual transaction and a later published estimate are not interchangeable evidence.
Start with the authority, instrument, purpose and timing. Intervention can occur through spot transactions, derivatives or other arrangements, and institutional responsibility differs across countries. A rumor that a central bank was active is weaker evidence than an official release. Even an official aggregate may not identify the exact intraday moments at which transactions occurred.
Balance-sheet releases can help confirm an operation, but reserve changes are not transaction amounts by themselves. If foreign securities rise in value or the reporting currency depreciates, the domestic-currency value of reserves may rise without a purchase. Conversely, intervention through a forward can create a future obligation without immediately changing gross spot reserves. Reconcile valuation, income, maturities and derivative commitments before using the reserve stock as a proxy for how much currency was bought or sold.
Separate sterilized and unsterilized effects
An unsterilized intervention can change domestic monetary conditions through its effect on monetary liabilities. Sterilization uses offsetting operations to limit that effect. The distinction matters because an exchange-rate response may reflect monetary-policy changes as well as the foreign-currency transaction itself. Treating the two as identical confuses mechanisms.
Sterilized intervention may still affect markets through signals, asset supplies or market functioning. Whether it succeeds depends on the circumstances rather than a universal rule. A credible action aligned with broader policy can differ from an attempt to resist persistent pressure while other policies point the opposite way. An analyst should state which channel is proposed and what evidence supports it.
Consider the opposite direction to the worked example: an authority buys foreign currency and supplies domestic reserves. To sterilize the reserve increase, it might sell domestic securities or use another liquidity-absorbing instrument under its operating framework. The foreign assets remain on its balance sheet, but the reserve effect has been offset. Sterilization therefore does not mean reversing the FX trade; it means changing a different balance-sheet leg so that one monetary consequence is neutralized.
Avoid the unlimited-resources story
The ability to issue domestic currency does not make every exchange-rate objective costless. Buying foreign assets can create balance-sheet risk and complicate domestic objectives. Supporting a domestic currency by selling foreign assets faces a different resource constraint. Gross reserves alone may overstate immediately usable resources if assets are encumbered or accompanied by foreign-currency liabilities.
A research note should distinguish liquid resources, announced commitments and contingent obligations. Do not convert an impressive reserve total into a precise number of days a currency can be defended without assumptions about the scale of pressure. Such estimates are highly sensitive to behavior and can become self-invalidating when participants change their expectations.
The two intervention directions have asymmetric constraints. An authority selling foreign reserves needs usable foreign-currency assets or access to borrowing. An authority buying foreign currency can issue its own liabilities, but must still contend with inflation objectives, interest costs, asset risk and political constraints. If domestic sterilization liabilities pay more than reserve assets earn, maintaining the position can carry a recurring cost. Neither direction supports the claim that intervention is unlimited or economically free.
Market impact can be temporary
A sharp initial price reaction may represent surprise, reduced market depth or traders reducing positions. It does not establish a permanent change in the equilibrium exchange rate. Conversely, the absence of a dramatic immediate move does not prove that an operation had no stabilizing effect; the relevant counterfactual is unobservable.
Use several horizons and compare broader conditions. Did volatility decline? Did liquidity improve? Did policy expectations change? Did similar currencies move at the same time? These questions improve interpretation without solving causal identification perfectly. Avoid selecting only interventions followed by large reversals, because unsuccessful or ambiguous episodes are necessary to assess the limits of the narrative.
Evaluation is difficult because intervention is usually a response to pressure, not a randomly assigned experiment. A currency might fall after support operations yet have fallen much further without them. It might also rebound for unrelated reasons. This selection problem is why a before-and-after chart cannot establish effectiveness on its own. Comparison currencies, controls for concurrent news and clearly stated horizons improve the analysis, but they do not make the missing counterfactual observable.
Build a disciplined event study
For educational analysis, list all identified interventions in a defined period and record when the information became public. Use consistent exchange-rate windows and note concurrent economic announcements. Separate official transaction data from press reports. If publication arrives with a delay, do not pretend a historical trader knew the final series in real time.
Stress scenarios should include no intervention, an unexpected intervention, repeated intervention and an eventual policy change. None should be presented as the most likely outcome without evidence. A position built around a presumed floor can fail through a gap before an ordinary exit order executes. Understanding the policy mechanism is useful; assuming protection from it is a different and much stronger claim.
For a useful counterfactual exercise, write two paths with identical initial intervention but different subsequent domestic policy. One path reinforces the stated currency objective; the other weakens it. Explain why identical first-day transactions need not generate identical longer-run results. This guards against extrapolating the size of a single operation into a durable price target.
Match the outcome measure to the announced objective. An operation intended to restore orderly trading should be assessed using measures such as depth, spreads and price discontinuities as well as the exchange-rate level. An operation intended to resist persistent appreciation raises a different question. Judging every intervention solely by whether the currency reversed the next day can label a liquidity intervention a failure while missing whether its actual objective was achieved.