Read the business behind the ticker
Connect revenue, profit, cash and debt without mistaking one strong headline number for a healthy business.
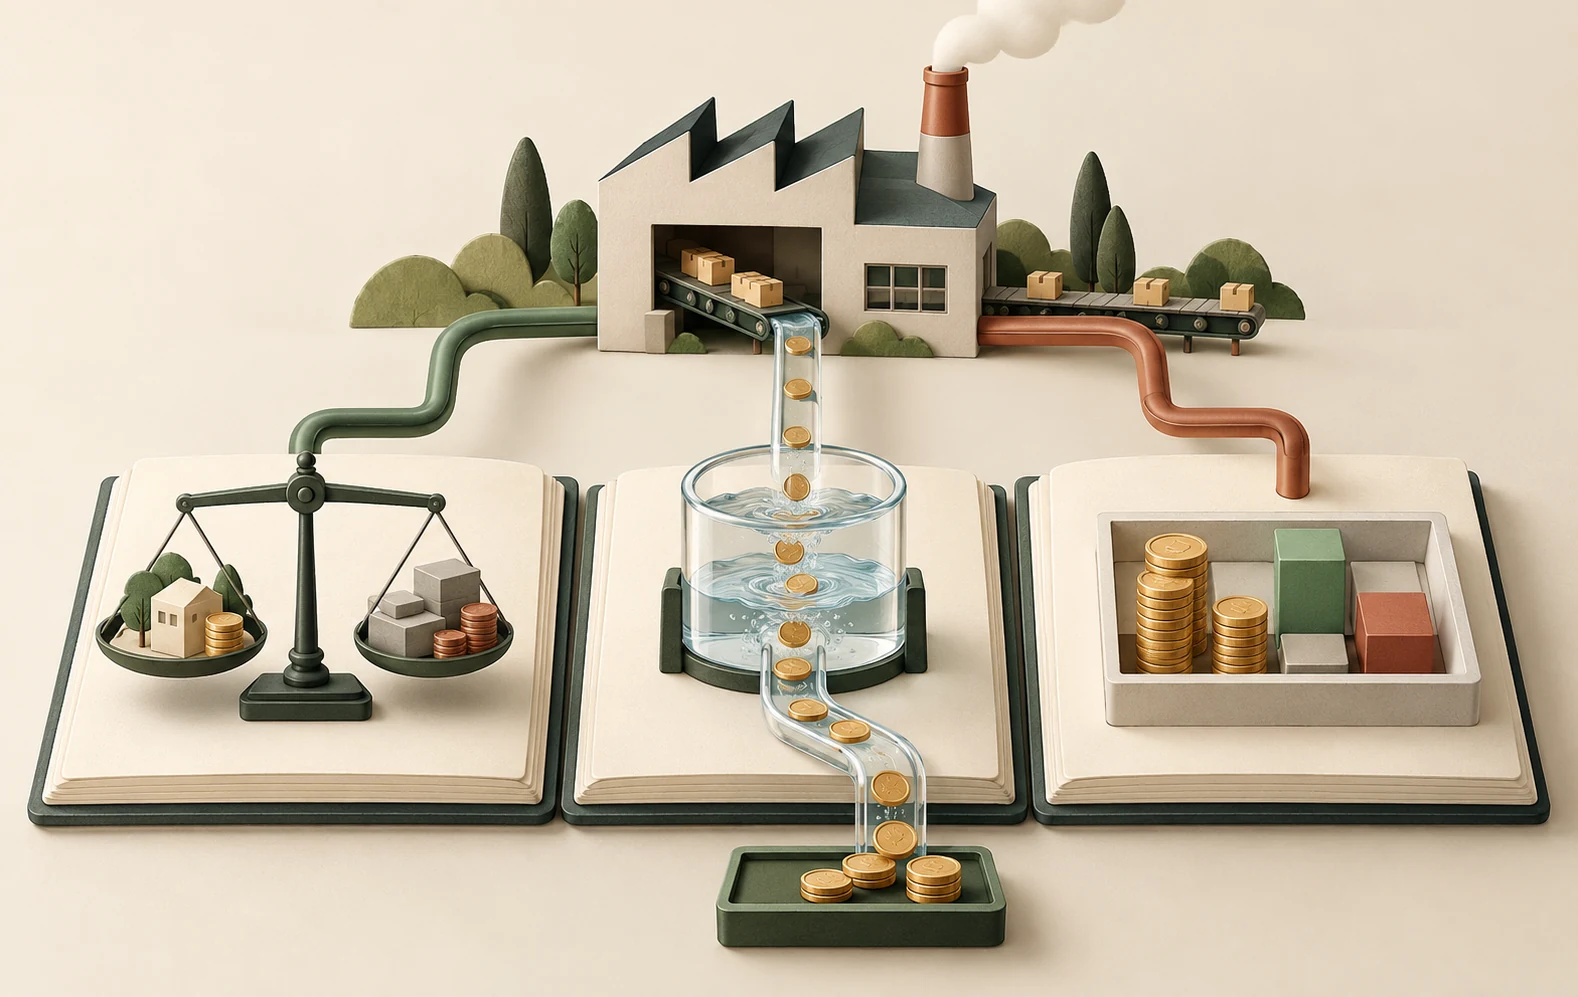
Three views of the same company
Financial statements answer different questions. The income statement describes revenue and expenses over a period. The balance sheet describes assets, liabilities and equity at a particular date. The cash-flow statement explains changes in cash over a period. Reading one without the others is like assessing a household from its salary while ignoring its bills, savings and loan repayments.
Revenue is not profit, and profit is not automatically cash collected. A business may recognize revenue before a customer pays. It may spend cash on equipment whose cost is allocated to expenses over several years. These timing differences are not automatically suspicious, but they create questions that a single earnings-per-share figure cannot answer.
Follow one transaction
Imagine a fictional equipment company sells a machine for $10,000 on credit. Revenue and a receivable can appear before the customer sends payment. Inventory leaves the balance sheet and an associated cost enters the income statement. Later collection changes receivables into cash rather than creating a second sale. Following that sequence prevents double-counting and explains why growing sales can coexist with strained cash availability.
Now imagine customers begin paying more slowly. Receivables rise faster than revenue, while cash collection weakens. Possible explanations include seasonal timing, different contract terms, a changing customer mix or collection problems. The ratio is a starting question, not a verdict. Notes and management's explanation should be checked against the actual numbers over multiple periods.
Separate operations from financing
New borrowing increases cash but does not show that customers are generating more cash for the business. Issuing shares can also raise cash while reducing existing holders' percentage ownership. Conversely, repaying debt consumes cash without necessarily reflecting a deterioration in the company's products. The cash-flow categories help keep these mechanisms separate.
Useful comparisons depend on the industry. Inventory is central to a retailer but may be relatively unimportant to a software business. A bank's balance sheet requires different interpretation from a manufacturer’s. Compare like with like, and note differences in accounting policies, fiscal periods and acquisition activity before treating a ratio as evidence of superiority.
Read the uncomfortable sections
Footnotes explain assumptions, commitments and accounting choices that do not fit in a headline table. Management commentary can explain changes, but it remains management's account of its own business. Audit opinions, related-party transactions, debt maturities and customer concentration deserve attention. An adjusted earnings measure may illuminate a business, but it should be reconciled with the relevant reported measure rather than accepted as a replacement.
For practice, create a one-page bridge between net income and operating cash flow, then list three unresolved questions. Keep the units visible: thousands, millions and per-share figures should never be mixed. This exercise develops a more useful habit than copying dozens of ratios without understanding what caused them to change.
Make the cash balance tie out
Before interpreting a financial ratio, check that the statements connect. In a simplified example, a company opens the year with $8 million cash, generates $5 million from operations, spends $7 million on equipment, borrows $4 million and pays a $1 million dividend. Closing cash is $9 million: 8 + 5 − 7 + 4 − 1. Cash rose even though operating cash generation did not cover equipment spending. The borrowing explains how the company financed the difference and the distribution.
A real reconciliation may also contain currency effects, business acquisitions and changes in restricted cash. Follow the company's stated cash definition rather than forcing every balance-sheet label into one total. If the statement reconciles cash and restricted cash together, comparing it with an unrestricted-cash line alone creates an artificial mismatch.
There is also a fourth major statement worth opening: changes in shareholders' equity. It helps connect retained earnings, distributions, share issuance, repurchases and other movements in owners' recorded capital. A higher closing equity balance can result from newly issued shares rather than from better operations. The SEC's financial-statement guide introduces these connections. None of the balances is a standalone estimate of what the shares should trade for.
Check what a reporting period actually contains
A quarterly filing may present three months of income-statement activity alongside a year-to-date cash-flow statement. Comparing the two without adjusting the periods can produce a convincing but meaningless cash-conversion ratio. Write the start date, end date and unit beside each number before calculating anything. Also check whether the comparable business changed through an acquisition, disposal or discontinued operation.
Suppose nine-month operating cash flow is $90 million and six-month operating cash flow was $55 million. The implied third-quarter amount is $35 million, assuming the reporting scope and definitions are consistent. It would be wrong to compare the full $90 million with third-quarter profit. Subtracting cumulative periods is a useful technique, but it should not conceal a restatement or a change in classification.
Finally, distinguish a reporting date from a publication date. A December balance sheet released in February describes December conditions. Events discussed after the reporting date may change the assessment even though they are absent from that closing balance. Keeping both dates in the research note makes it easier to understand what was known when a particular valuation or financing decision was made.