Dividends, splits and the total-return picture
Follow the money and share count through corporate actions without confusing a distribution or a split with newly created wealth.
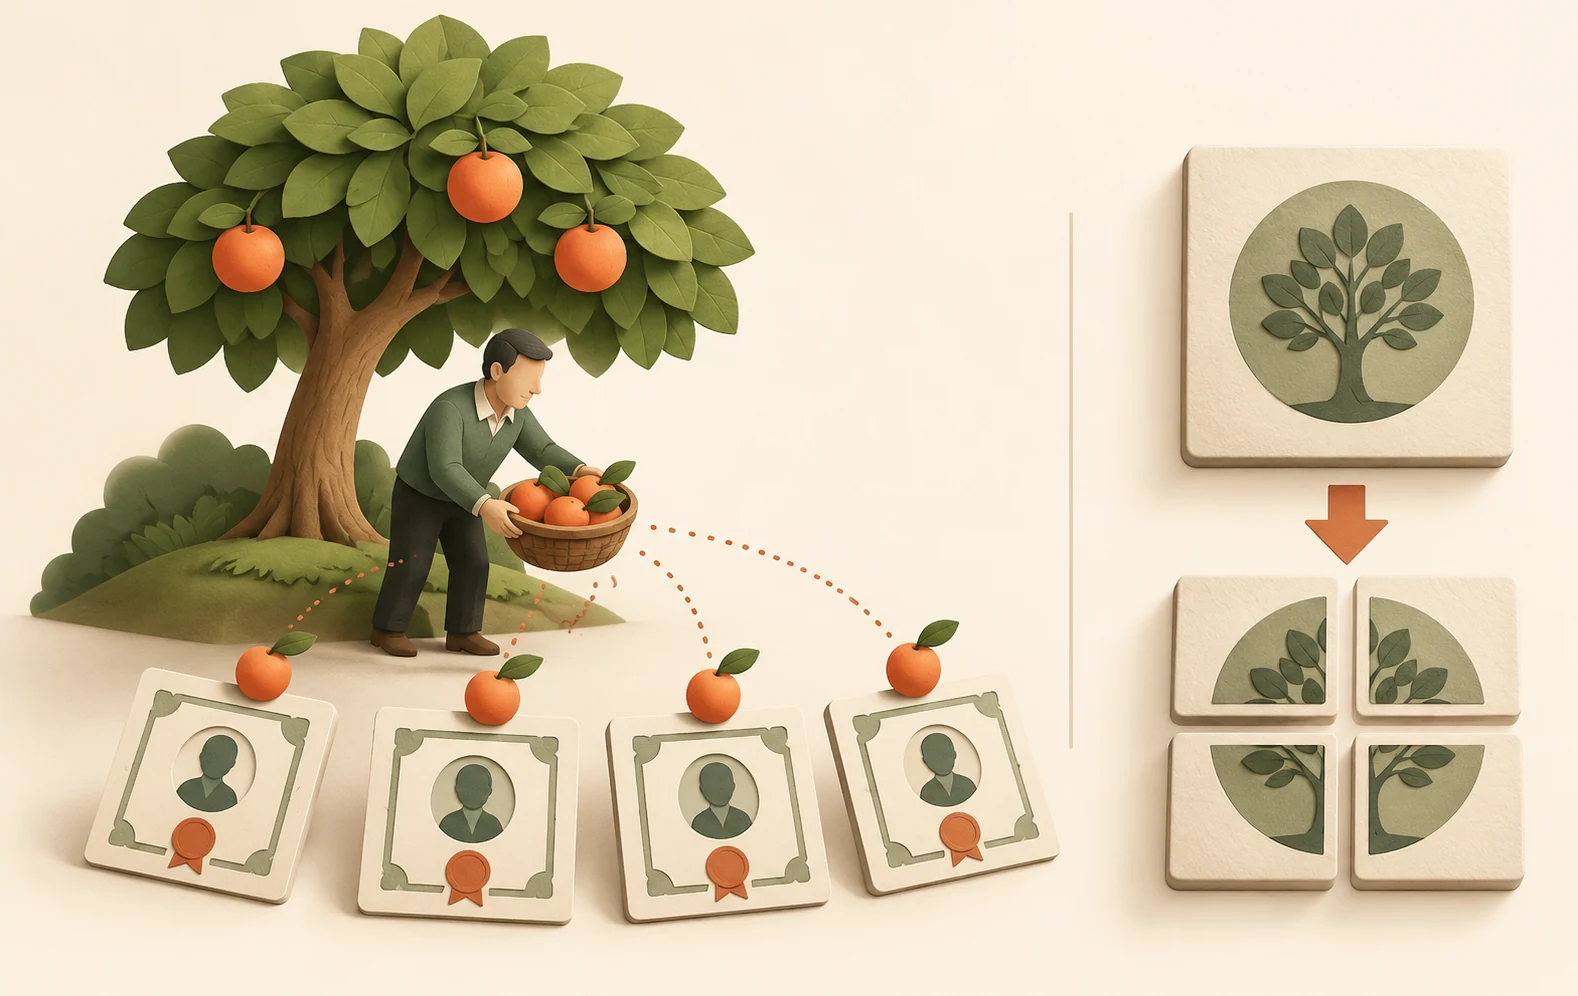
A dividend moves value out of the business
A cash dividend distributes company cash to eligible shareholders. It is one component of total return, alongside changes in the share price. It is not free money added to an otherwise unchanged investment. All else equal, a share trading without entitlement to an upcoming distribution should be worth less than a share carrying that entitlement, although ordinary market movements can obscure the adjustment.
The declaration, record, ex-dividend and payment dates describe different stages. Eligibility rules depend on the market, settlement arrangements and type of distribution; unusually large or special distributions can follow different procedures. Use the issuer's announcement and the relevant exchange notice rather than a memorized calendar shortcut. Buying after the applicable ex-dividend date normally means the next distribution belongs to the seller, not the new buyer.
Yield needs a denominator and a question
Dividend yield compares a dividend amount with share price. A high displayed yield can arise because the price has fallen, not because the business has become more generous. It may use a historical payment that will not recur. Companies can reduce or suspend dividends, and borrowing money to maintain a payment is different from funding it comfortably from ongoing operations.
A useful analysis distinguishes ordinary distributions from one-time payments and examines their funding. It also specifies whether the displayed figure is trailing, indicated or forecast. An estimate of next year's yield is still an estimate. Withholding, personal taxes, account type and currency conversion can alter the cash actually retained; these matters depend on jurisdiction and individual circumstances.
Splits change units, not the whole pie
In a simple two-for-one stock split, each old share becomes two new shares and the theoretical price per share halves. The shareholder's proportional interest is unchanged before other market movements. A reverse split does the opposite. Neither operation alone improves the company's factories, customer relationships or earning power.
Historical charts and per-share data often adjust for splits, so an old price on a current chart may differ from the price printed in an old news story. Compare consistently adjusted series. Other corporate actions, such as rights issues, mergers or spinoffs, can involve choices, deadlines, fractional entitlements and tax consequences; their terms cannot be inferred from the simple split example.
Build a total-return ledger
For practice, record opening value, purchases, sales, distributions, fees and closing value separately. Reinvesting a dividend purchases additional shares; it is not the same as the share price having risen by that amount. If comparing strategies, use consistent treatment of distributions and cash flows. Comparing a price-only series with a dividend-reinvested series can make identical market exposure look very different.
Corporate-action announcements also create operational risks. An order may be adjusted or canceled under a broker's policy, and fractional holdings may be treated differently. Reading the notice is part of understanding the position. This is especially important when a similarly named derivative provides a contractual adjustment rather than the shareholder's actual entitlement.
Look at what remains after the payment
A dividend can be comfortably covered by reported earnings while leaving little room for the cash the business must spend next. For a fictional company, suppose operating cash flow is $80 million, necessary capital spending is $35 million and the annual cash dividend is $30 million. The remaining $15 million must absorb any further working-capital need, debt repayment or unexpected expense. A profit-based payout ratio alone cannot describe that room for maneuver.
Avoid treating every investment dollar as optional simply because management calls it growth spending. A retailer may need to refurbish stores to remain competitive; a software company may need continuing product work to retain customers. Equally, a large one-time expansion can make current cash coverage look unusually weak even when the recurring distribution is modest. The task is to explain the spending, not to force all businesses through one preferred ratio.
For a dividend-reinvestment example, keep the purchase of new shares visible. A $100 distribution reinvested at $25 buys four additional shares before charges. Those four shares then participate in subsequent price changes and distributions. The cash receipt and the reinvestment are two events, even if an account service performs them automatically. Their actual dates, prices and tax treatment should not be replaced by an assumption that reinvestment occurred at the old closing price.
Check the records on both sides of a corporate action
Before a split or other action, save the quantity, identifier, outstanding orders and relevant notice in a paper exercise. Afterward, reconcile what changed. In a simple four-for-one split, 25 shares become 100 and a $120 reference price becomes approximately $30, leaving the same $3,000 value before market movements. A chart showing the old $120 price beside the new $30 price without adjustment would falsely suggest a 75% collapse.
More complicated events deserve a fresh ledger. A spinoff can leave the investor with interests in two businesses; the parent share price alone no longer captures the whole holding. A cash payment in place of a fractional entitlement also belongs in the reconciliation. Do not infer the exact entitlement from a familiar label: use the issuer's terms, the relevant market notice and the intermediary's processing information.
The aim is to explain every movement in units and cash before drawing a performance conclusion. If the numbers do not reconcile, investigate settlement and processing dates first. An apparent loss or windfall may be a missing leg of the corporate action rather than a change in economic wealth.