Buybacks: per-share arithmetic versus value creation
Evaluate repurchases through price, financing and the share count that actually remains.
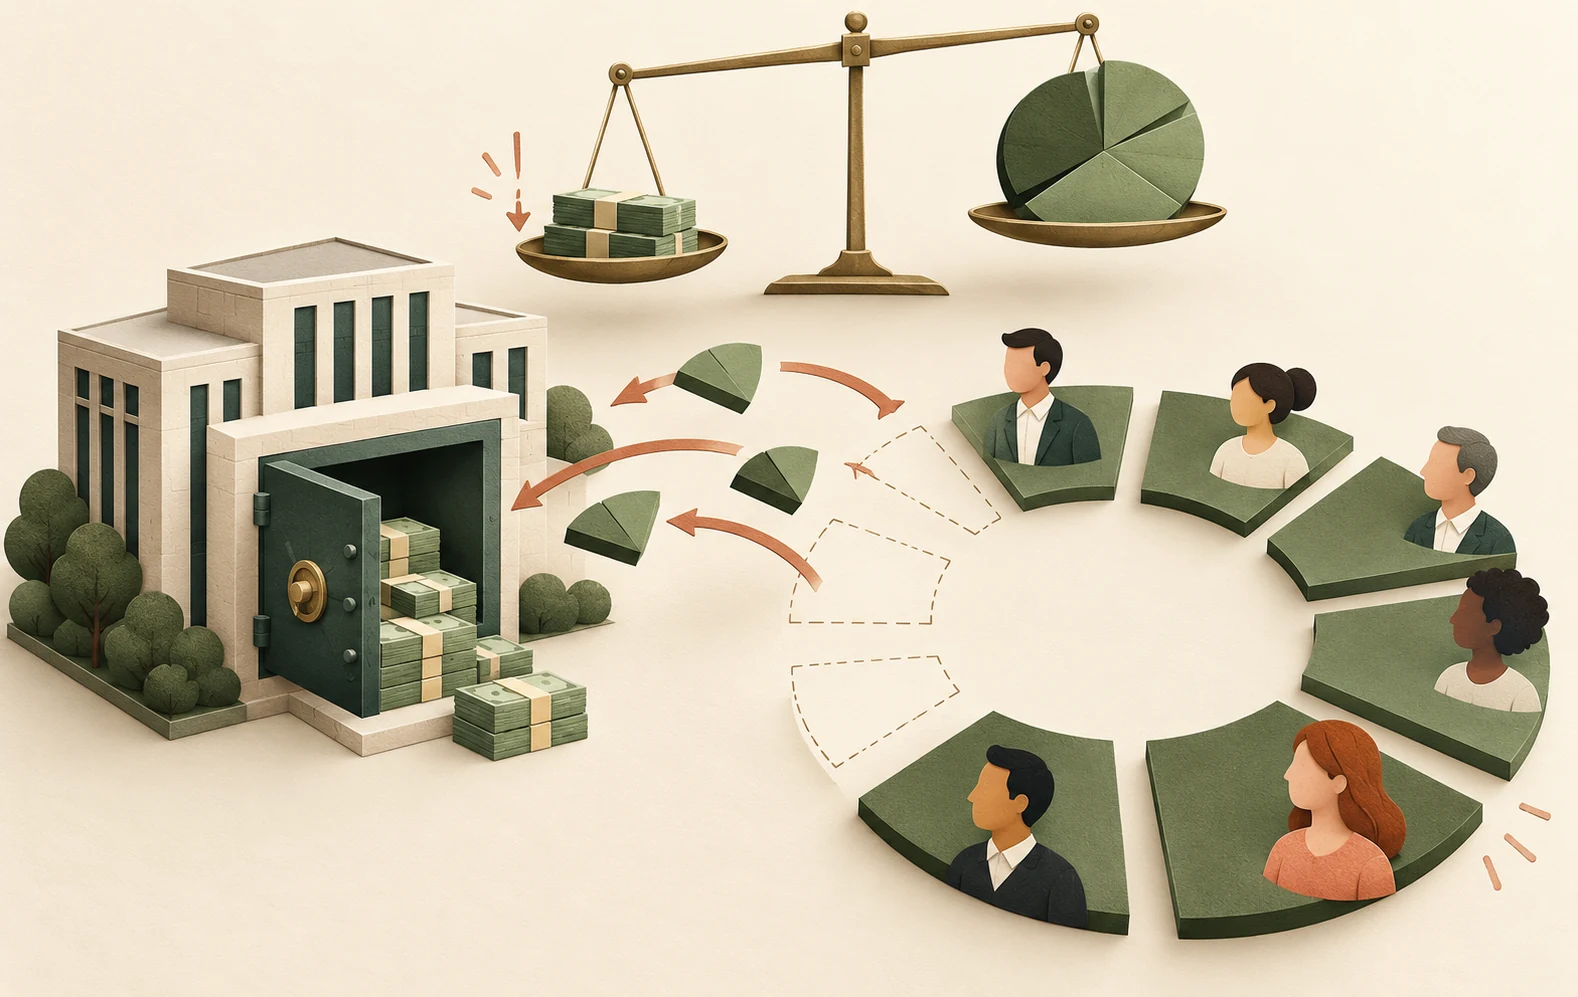
The denominator can move without the business improving
A share repurchase uses corporate resources to acquire outstanding shares. With fewer shares, unchanged total earnings can translate into higher earnings per share. That mechanical increase does not establish that the business became more productive or that continuing owners gained economic value. The price paid and the alternative uses of the money are central to the assessment.
Distinguish an authorization from completed transactions. A board can authorize a maximum amount without obligating the company to spend it immediately or at all. Read the actual cash outflow, shares acquired and average price over the reporting period. Compare them with shares issued through compensation, acquisitions or capital raising. Gross repurchases can sound impressive while the net share count barely changes.
Account for what leaves the company
Cash used in a repurchase is no longer available for interest income, reinvestment or resilience. Debt-funded repurchases add financing obligations. Comparing earnings per share before and after a repurchase while assuming earnings remain unchanged can therefore overstate the improvement. Estimate foregone after-tax interest or incremental financing expense where material, and distinguish a simplified arithmetic demonstration from a full valuation.
Consider a business worth more or less than the repurchase price under a reasoned valuation range. Repurchasing below estimated value can transfer value toward continuing holders, whereas paying too much can destroy value even if earnings per share rise. Because intrinsic value is uncertain, the conclusion should remain conditional. Management's confidence is evidence about its stated view, not proof that the price was attractive.
Read the incentives and the cycle
A repurchase can offset employee issuance, return surplus cash or adjust capital structure. It can also help meet a per-share compensation target without a comparable increase in aggregate profit. Review incentive definitions and dilution trends before interpreting the headline. An improvement in return on equity after equity capital shrinks is another denominator effect that needs context.
Timing matters. A cyclical company may have the most cash and strongest trailing earnings near a peak, when its shares look deceptively cheap on a price-to-earnings basis. Large repurchases then can leave less flexibility in the downturn. Conversely, a depressed price does not automatically justify buying back stock if the business needs liquidity to survive. Test the repurchase against a financing stress case as well as a valuation case.
Compare credible alternatives
Evaluate a repurchase alongside debt reduction, dividends and operating investment. Do not assume that all proposed growth spending creates value or that all distributions signal a lack of opportunities. The relevant comparison is the expected return, uncertainty and flexibility of each available use. Sometimes preserving cash is valuable because it reduces the chance of emergency financing rather than because cash itself earns a high return.
Build a simple reconciliation: beginning shares, gross shares retired, shares issued, ending shares and weighted-average diluted shares. These measures differ because transaction dates and potential dilution matter. Pair it with a cash and debt reconciliation. A disciplined review can then explain whether per-share improvement came from operations, financing or denominator management. None of these mechanisms alone guarantees a favorable stock-price response, particularly when market expectations already anticipated the program.
Do not infer execution quality from the average repurchase price alone. Compare that price with the dates, volumes and conditions under which purchases occurred, then evaluate it against a valuation range that could reasonably have been estimated at those dates. A later price collapse does not prove the earlier decision was irrational, just as a later rally does not prove it was disciplined. Process, opportunity cost and financing resilience are more informative than a hindsight-only trading score.
Show the value left for the continuing owners
Start with a fictional company whose total equity is estimated at $1 billion, including $100 million cash available for distribution, with 100 million shares outstanding. Its assumed value is therefore $10 per share. If it spends that $100 million repurchasing shares at $8, it retires 12.5 million shares. Under the deliberately fixed valuation assumptions, $900 million remains for 87.5 million shares, or about $10.29 per share.
At a $12 repurchase price, the same cash retires about 8.33 million shares. The remaining $900 million is spread across about 91.67 million shares, giving roughly $9.82 per share. The operating business has not changed in either case; the difference comes from the price at which an ownership claim was removed. This makes the transfer to or from continuing holders visible without relying on an earnings-per-share headline.
The estimated $1 billion is an assumption, not a discovered fact. If the business deteriorates or the cash is needed to avoid distress, the exercise must change. It also ignores taxes, transaction costs, signaling and execution timing. Its purpose is to clarify why a repurchase cannot be assessed solely from the amount authorized or the percentage of shares retired.