Dollar funding stress and central-bank swap lines
Distinguish the need for currency funding from a directional currency view.
Funding demand is an obligation
An institution can need dollars because a dollar liability must be paid, even if it has no opinion about whether the dollar is cheap. Its assets may be long-dated, denominated in another currency or difficult to sell quickly. When refinancing becomes less reliable, the institution may prioritize obtaining usable cash over the price of that cash.
This creates a distinction between market liquidity and funding liquidity. A currency pair can trade frequently while a particular borrower struggles to obtain term funding on acceptable conditions. Conversely, a solvent institution can face a short-term mismatch. Solvency, collateral quality, maturity and currency denomination need separate entries in the analysis rather than a single label of stress.
An institution can be hedged against exchange-rate changes and still be short of cash. For example, a foreign investor may own a long-term dollar bond and use a short-term FX swap to obtain the dollars needed to finance it. The currency principals can be matched while the maturities are not. When the swap expires, dollars are owed regardless of whether the bond is still valuable. A hedge of price risk is not automatically a hedge of refinancing risk.
Maturity transformation creates rollover risk
Borrowing dollars for one month to finance a one-year asset leaves repeated refinancing needs. A favorable initial funding quote says little about the next roll during a crisis. If many institutions rely on the same short-term channel, simultaneous attempts to renew funding can increase spreads and pressure intermediaries' balance sheets.
For a practice balance sheet, identify every payment date rather than netting the entire year. A positive year-end asset value cannot settle an obligation due tomorrow unless it can be monetized. Include collateral haircuts and possible margin calls. The difference between economic value and immediately available cash explains why funding stress can force transactions that look unattractive on a long-term valuation basis.
A haircut converts collateral value into a smaller borrowing capacity. With $10 million of eligible securities and a 5% haircut, an illustrative lender advances $9.5 million. If the haircut rises to 15% with prices unchanged, capacity falls to $8.5 million. If the securities also fall to $9 million, capacity becomes $7.65 million. That $1.85 million reduction can create an immediate funding gap even before the institution realizes any loss by selling the assets.
What a central-bank swap line does
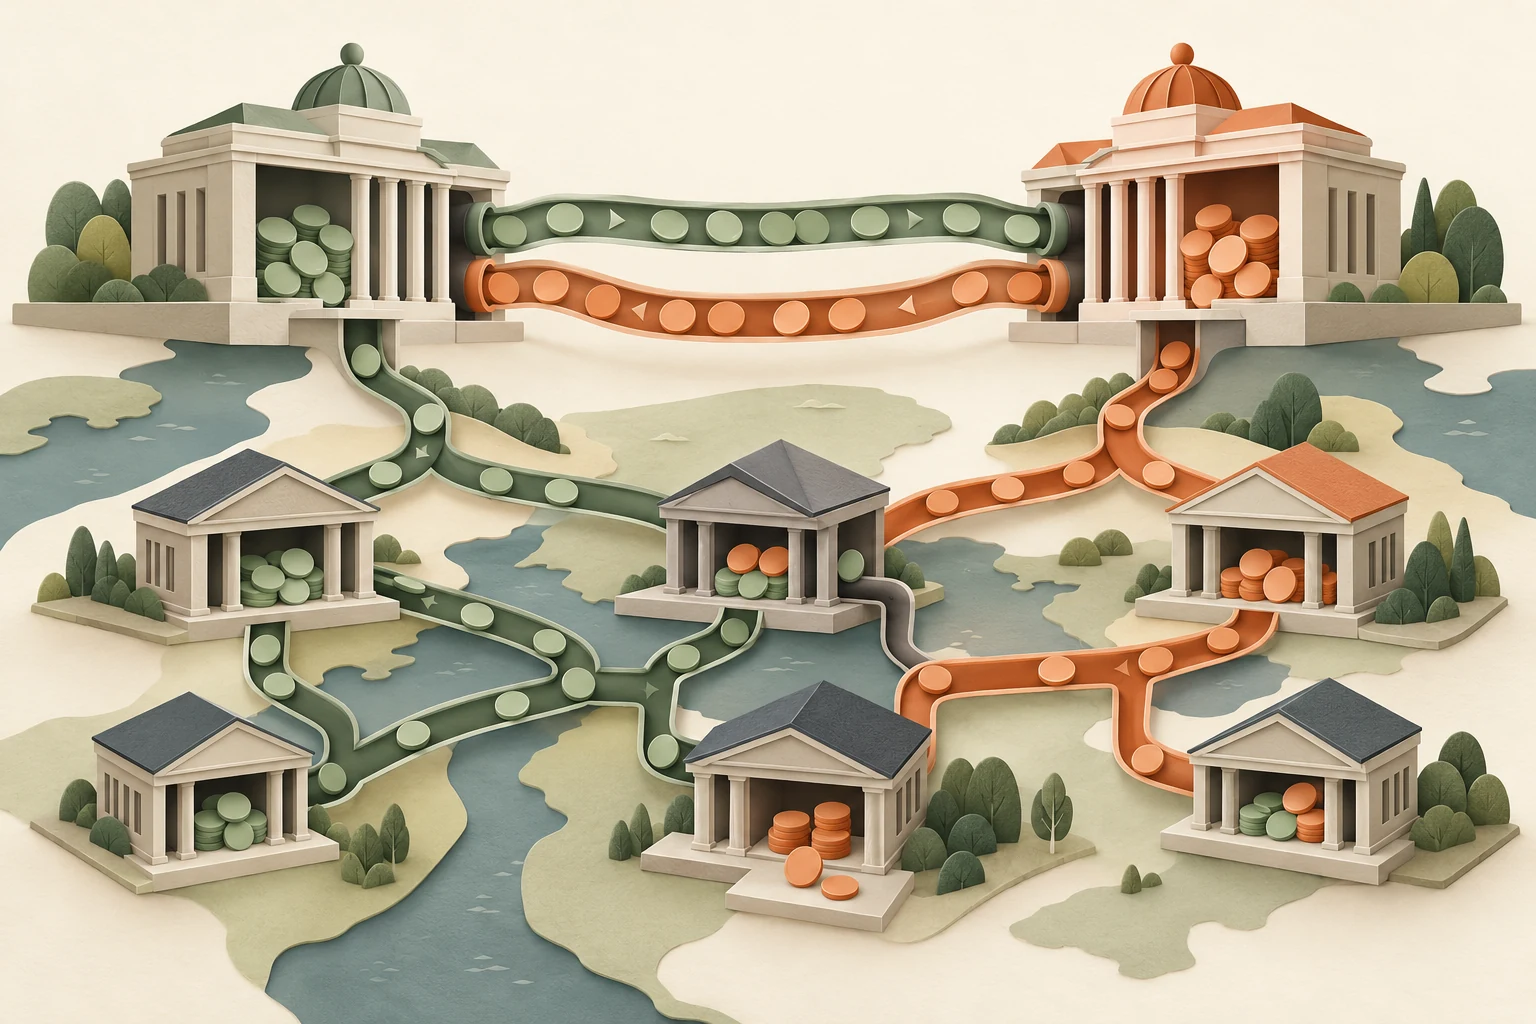
A central-bank liquidity swap is an arrangement between central banks, distinct from an ordinary trader's rolling forex charge. In the Federal Reserve's dollar liquidity arrangements, dollars are exchanged with a foreign central bank and the principal exchange is reversed at the same exchange rate under the agreement. The foreign central bank distributes dollars through its own operations subject to applicable terms.
This structure can support access to dollar funding, but it does not provide every market participant with unrestricted dollars. Eligibility, collateral, pricing, tenor and local operations matter. A swap line is not an instruction to buy risk assets or a guarantee that private credit losses disappear. It addresses a particular funding channel, not every possible weakness in a financial system.
The credit relationship has two distinct links. The Federal Reserve's counterparty in its dollar liquidity swap is the foreign central bank, not each institution borrowing dollars locally. The foreign central bank remains responsible for returning the dollars and bears the credit risk on its local loans. Reversing the principal exchange at the original exchange rate avoids exposing that principal exchange to subsequent currency movements; it does not imply that local borrowers face no repayment obligation or collateral discipline.
Observe several indicators
A single exchange-rate move cannot identify dollar funding stress. Examine compatible evidence such as cross-currency funding measures, short-term funding spreads, market depth and official operation usage. Each has interpretation limits. High usage can signal pressure, successful access to a backstop, or both; low usage can reflect calm conditions or reluctance and eligibility constraints.
Keep reporting delays in mind. A weekly official balance-sheet release and an intraday swap quote describe different time resolutions. Do not align them visually and infer exact causality. Document the release date and the reference period separately. If a facility is announced before it is used, prices may respond to the availability of insurance rather than to the later quantity drawn.
Build a funding ladder by currency and date: cash already available, contractual inflows, obligations, collateral calls and funding that must be renewed. Do not treat an uncommitted credit line as equivalent to cash or to a committed facility whose conditions are met. Settlement cutoffs can also make an expected same-day receipt unusable for an earlier payment. The useful measure is the largest cash shortfall along the path, not merely the surplus at the end of the quarter.
Translate the mechanism into a stress test
An educational funding stress test combines a currency move, a wider funding spread and a shorter available tenor. It also asks whether collateral loses value. These variables can reinforce one another: adverse prices create margin needs just as refinancing becomes more expensive. Modeling only the final spot conversion misses the path that can force liquidation.
The conclusion should identify cash needs and unresolved assumptions, not forecast a crisis. A useful research note explains which obligation creates demand, when it falls due, what funding channel might fail and what alternative exists. This framework remains useful even when the currency itself barely moves, because a funding problem concerns access and timing as well as price.
An operational checklist should distinguish a committed alternative funding source from an assumed ability to sell assets. State the settlement date and potential haircut for each alternative. A resource that arrives after the payment deadline is not equivalent to cash available beforehand, even if both improve the final balance-sheet position.
A backstop can change behavior before anyone draws on it, but that is an inference requiring care. A narrower funding spread after an announcement is consistent with reduced rollover anxiety; it can also reflect simultaneous policy measures or improved market sentiment. Compare timing and several indicators, then state what remains unresolved. Facility usage measures actual borrowing under specified terms, not the size of all funding needs across the financial system.