One dollar on the screen is not one dollar in the bank
Separate token price, redemption access, and platform custody before treating a stablecoin balance as available cash.
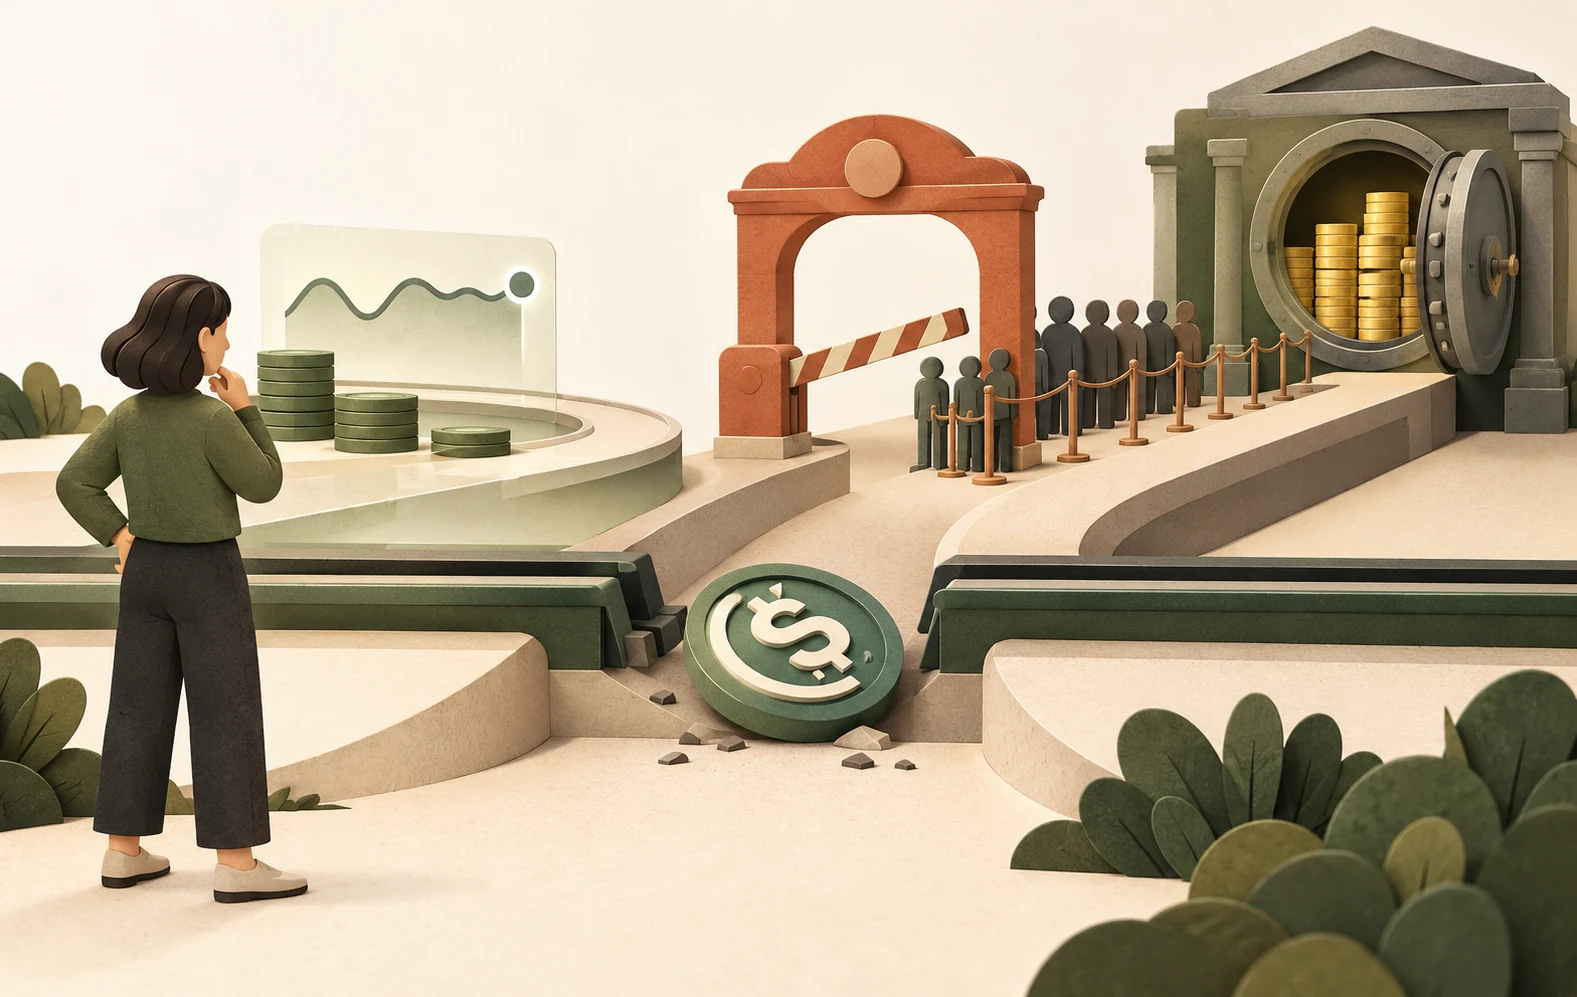
Conceptual illustration, not actual market data. Diagram labels may use a separate simplified example from the case.
The setup
Hypothetical educational case, not a recommendation to hold or trade any token. Harbor Dollar, abbreviated HBD, and the exchange in this story are invented. Elise holds 20,000 HBD, intended to track the US dollar, on a fictional trading platform. She has mentally labeled the position “cash.” A market discount and a withdrawal interruption reveal that price stability, legal redemption rights, and access to assets are three different questions.
Write down what is actually owned
Elise's dashboard values 20,000 tokens at $20,000 because the displayed reference price is $1. That display does not establish that she has a bank deposit, that she can redeem directly with the issuer, or that a withdrawal will settle immediately. For this case the fictional issuer only accepts direct redemptions from approved institutional customers. Elise must sell through a secondary market or use her exchange's conversion service.
The Federal Reserve's research on stablecoins distinguishes reserve quality and redemption dynamics from the simple promise of a peg. FINRA's custody material separately highlights risks around exchange wallets and private-key control. These concepts motivate the case, but the particular access restrictions, fees, and outcomes below are invented. A real analysis would read the exact token terms, reserve disclosures, platform agreement, and applicable protections instead of inferring rights from a product name.
The first executable exit is below the headline quote
After an invented reserve concern, the indicative market price drops to $0.94. That implies a $18,800 mark, a $1,200 decline from par. Elise's entire 20,000-token sale would consume several price levels, producing an estimated average execution at $0.935. Gross proceeds would be $18,700. A 0.30% trading charge costs $56.10, and a $25 withdrawal charge leaves $18,618.90 in expected bank proceeds if settlement succeeds.
Relative to her assumed $20,000 starting value, that is a $1,381.10 shortfall, or about 6.91%. The $100 difference between the $0.94 mark and the $0.935 average execution is market impact or execution shortfall already embedded in proceeds. It should not be added again. The bank withdrawal fee is distinct. This ledger makes the decision about spendable dollars rather than a last-traded token price that may apply to only a tiny transaction.
The platform freezes withdrawals
Now suppose the exchange suspends token and cash withdrawals before Elise submits the sale. An on-screen conversion may still be possible, but a dollar-denominated platform balance is not necessarily immediately withdrawable bank money. Selling HBD could remove token-price exposure while leaving the platform exposure intact. Conversely, moving tokens to a self-controlled wallet, if transfers were available, could change custody exposure while retaining the token's issuer and price risks.
To make the distinction concrete, imagine the token later returns to $1 but the platform ultimately distributes only 80% of customer balances after a prolonged process. On a simplified $20,000 claim, recovery would be $16,000 before other expenses. This is a separate scenario, not an additional loss automatically stacked onto the earlier sale calculation. Timing, legal priority, and actual recovery could differ radically. A price recovery alone would not have solved the access problem.
Compare choices without inventing certainty
If the platform remains functional, selling at the modeled $18,618.90 net amount trades uncertain future recovery for a specified estimated immediate exit. Waiting for $1 might recover the discount, but could also expose Elise to a deeper decline or a closure. Buying more because the token is “on sale” would increase exposure to the very issuer and redemption assumptions now under question. A discount is not proof of an arbitrage available to this particular holder.
Elise can model a deliberately simple two-outcome wait: 70% chance of receiving $20,000 and 30% chance of receiving $12,000. The probability-weighted amount is $17,600 before costs and time value. These probabilities are invented sensitivity inputs, not estimated odds. Changing the recovery probability to 90% produces $19,200. The wide change illustrates why an expected-value calculation is only as informative as its assumptions, especially when the lower outcome would disrupt essential spending.
Separate operating cash from risk capital
Before any future position, Elise would distinguish money needed for near-term bills from capital explicitly allocated to risky market infrastructure. A token used as trading collateral can face a haircut or changing eligibility exactly when its market value falls. A token posted to a lending contract also adds liquidation mechanics; it is not the same exposure as a freely transferable wallet holding. Platform concentration can compound all of these dependencies.
Operational preparation includes verifying the destination network, testing a small transfer where appropriate, keeping enough native network currency for fees, and understanding who controls recovery credentials. Self-custody reduces some intermediary dependencies but creates irreversible key-management and transaction risks; it is not a universal safety upgrade. The case's practical lesson is to map the full route from an asset claim to usable cash, including every institution, contract, conversion, and settlement step on that route.
Calculate the recovery probability the comparison requires
Using the case's invented waiting outcomes of $20,000 or $12,000, what probability of the higher recovery would match the accessible $18,618.90 immediate exit? The break-even probability is about 82.74%, before extra waiting costs. This calculation reverses the question: it reveals how optimistic the recovery assumption must be, rather than presenting an invented probability as evidence.
12 000 + 8 000p = 18 618.90 → p ≈ 82.74%
If both recoveries arrive one year later and a purely illustrative 5% discount rate is applied, the threshold rises to about 94.37%. Actual probabilities, timing and costs remain unknown. Even an expected value above today's exit does not make waiting suitable for essential spending: a large low-outcome loss or lack of access can matter more than the arithmetic average.
Where the reasoning goes wrong
Calling a token balance insured cash
A dollar reference price does not establish bank-deposit status or protection.
Assuming direct redemption
The ability to trade a token is different from a contractual right to redeem with its issuer.
Confusing price recovery with access
A restored peg cannot by itself unfreeze a platform or resolve a custody claim.
Test the decision, not your memory.
An accessible 8,000-token balance sells at an average $0.97. The fee is 0.25% of gross proceeds and the withdrawal charge is $15. Calculate net dollars and the shortfall from $8,000.
Show the worked answer
Gross proceeds are 8,000 × $0.97 = $7,760. Trading fees are $7,760 × 0.0025 = $19.40. After the $15 withdrawal charge, net proceeds are $7,725.60. The shortfall is $274.40, or 3.43%. This assumes the sale and withdrawal both complete; it does not quantify custody failure.