Five positions, one underlying bet
Different tickers and asset classes can share the same vulnerability when liquidity disappears.
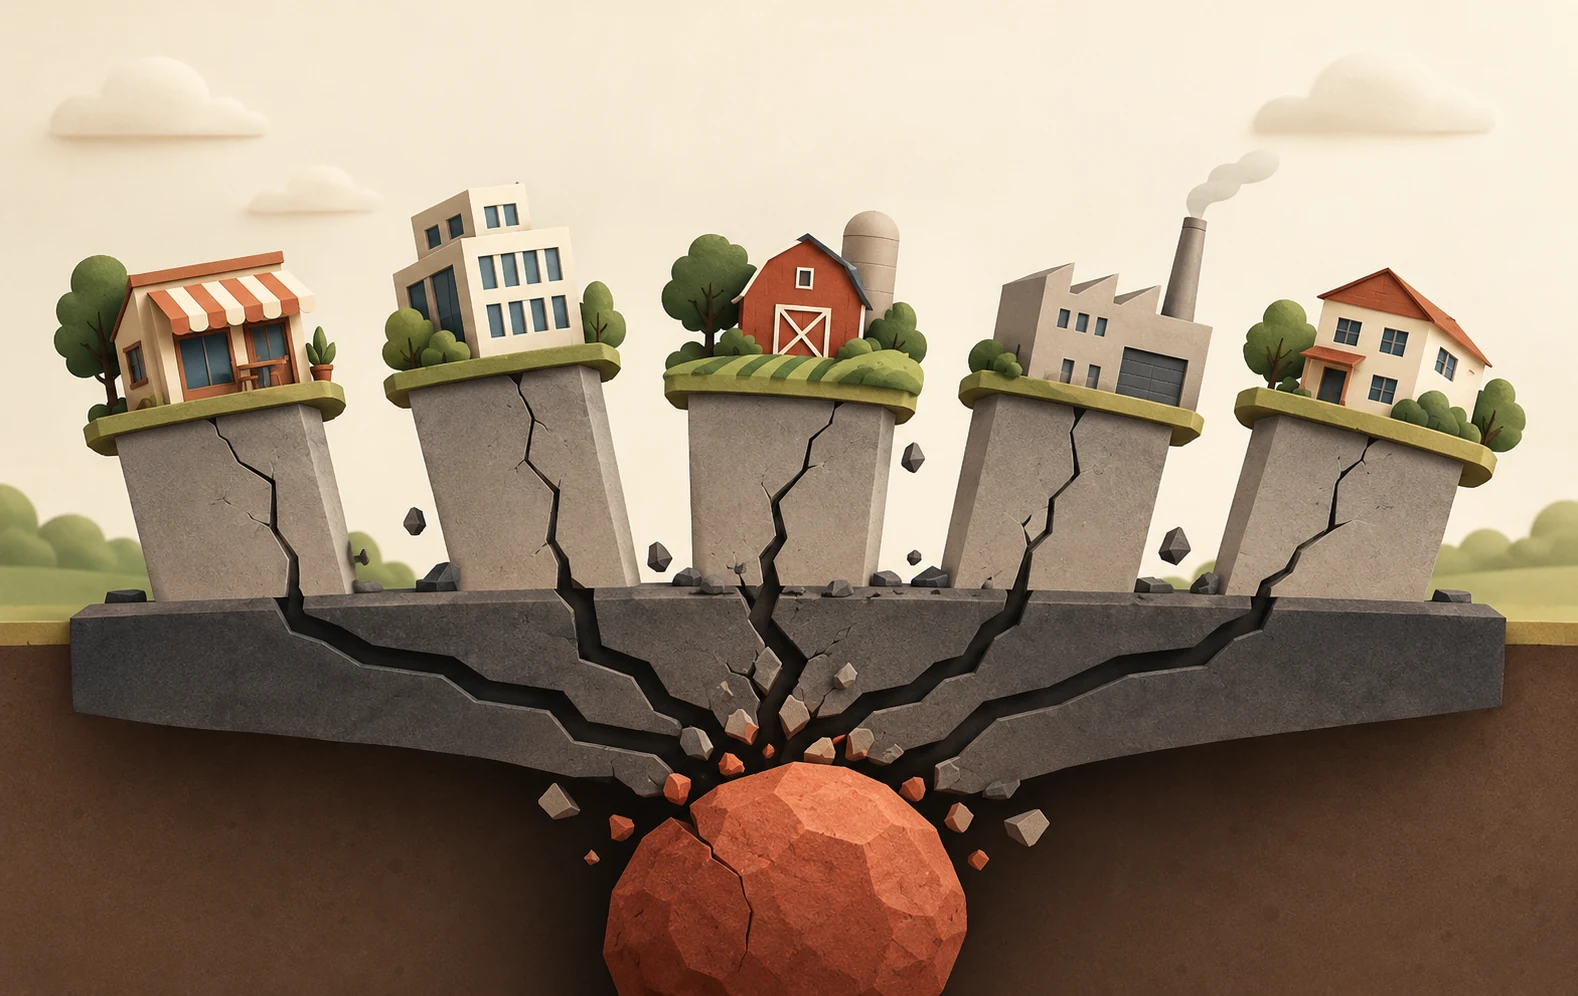
Conceptual illustration, not actual market data. Diagram labels may use a separate simplified example from the case.
The setup
Hypothetical educational case, not an allocation recommendation. All holdings, returns, and funding assumptions are invented. Omar has a $50,000 portfolio: $15,000 in a fictional growth-stock basket, $10,000 in a fictional semiconductor basket, $10,000 in a speculative crypto basket, $5,000 in a leveraged foreign-exchange carry exposure measured by allocated equity, and $10,000 in unencumbered cash. He calls it diversified because it has five labels.
Look through the labels
The growth and semiconductor baskets can overlap in companies, valuation sensitivity, and demand for risk capital. The crypto basket may also be sensitive to speculative appetite. The currency position may rely on investors continuing to finance risk-taking. These are proposed common drivers for the invented scenario, not a claim that all of these markets always move together. Cash is the one bucket explicitly assumed not to suffer market-price loss here.
Omar's position list does not include look-through holdings, leverage, or financing dependencies. It also mistakes allocated equity in the FX account for notional exposure. A proper inventory would record both, along with counterparty and currency denomination. Five lines on a screen are not five independent sources of risk. Historical correlations could help describe past behavior, but a quiet sample cannot rule out a future joint shock.
Apply one coherent stress
For a hypothetical liquidity shock, assume the growth basket falls 12%, semiconductors 15%, crypto 25%, and the allocated FX equity loses 20%. The dollar losses are $1,800, $1,500, $2,500, and $1,000 respectively. Together they total $6,800, leaving $43,200 before execution costs. The portfolio decline is 13.6%, despite none of the risky sleeves initially exceeding 30% of total capital.
The FX percentage is a loss on its allocated equity, not a 20% move in an exchange rate. This distinction prevents an accidental leverage error. If the $5,000 supported $25,000 of notional exposure, a simplified 4% adverse underlying move could produce a $1,000 loss before costs. Actual cross-currency translation, margin arrangements, and nonlinear instruments would require a more detailed model.
The shock’s contribution can be read directly from the loss ledger. Crypto supplies $2,500 of the $6,800 price loss, about 36.8%, although it represents only 20% of initial capital. Growth shares supply about 26.5%, semiconductors 22.1% and the FX sleeve 14.7%. These are contributions to this particular scenario loss, not estimates of everyday volatility contributions. A different shock can produce a different ranking, so the percentages should travel with the assumptions that generated them.
Add the cost of needing liquidity now
Suppose Omar must close the risky sleeves during this shock. Their stressed values are $13,200, $8,500, $7,500, and $4,000, totaling $33,200. An invented aggregate execution cost of 0.75% of those liquidation values is $249. Total portfolio damage becomes $7,049, or 14.098% of starting wealth, leaving $42,951. Applying 0.75% to the original $40,000 risky value would be a different assumption and should be labeled rather than mixed into this calculation.
A sale is not the only path. If no leverage or cash need forced the issue, he could retain the exposures, but their future recovery would remain uncertain. Waiting is an active exposure decision, not the absence of a decision. Conversely, if the FX provider requires additional collateral, Omar may have to move cash quickly even while the other positions are falling. Settlement times can make ostensibly liquid wealth unavailable before a deadline.
Test a different construction
For comparison only, halve each risky sleeve and hold the released $20,000 as additional unencumbered cash. The portfolio now has $30,000 cash and $20,000 across the same risky exposures. Under exactly the same percentage shocks, price loss falls to $3,400, or 6.8%. Stressed risky value is $16,600, so the assumed 0.75% exit cost is $124.50. Total damage is $3,524.50, or 7.049%.
This is not a free improvement. Under favorable risky-asset returns, the reduced exposure would participate less. Cash also has inflation and opportunity-cost considerations, and the assumed cash value depends on where it is held. The comparison merely shows that reducing a common exposure can change the stressed dollar loss more predictably than adding another highly related ticker. Selecting a supposedly defensive asset would require its own scenario rather than assuming it must rise.
Build a decision rule that can be audited
Omar sets an educational review threshold of a 10% portfolio decline in this particular stress, not as a universal risk rule. His original portfolio fails; the reduced-exposure version passes that modeled test. Passing does not establish safety against all shocks. A different scenario involving cash access, inflation, currency movements, or a single counterparty failure could reorder the results. Scenario coverage matters as much as the numerical threshold.
The next review groups exposure by economic driver, checks overlapping holdings, and records which assets can actually be converted to usable cash. It distinguishes gross exposure, net exposure, and posted collateral rather than compressing them into one number. Diversification remains useful, but it must be evaluated through relationships and failure modes, not counted by product names. The goal is to discover the portfolio's shared dependencies before an adverse move makes them obvious.
Test the cash reserve and the shared dependencies separately
The original calculation assumes all $10,000 of cash remains accessible and unchanged in value. Challenge access without immediately inventing a loss. Suppose $6,000 is temporarily unavailable for transfer while $4,000 remains usable, and a separate $5,000 collateral top-up is due before any asset sale can settle. Omar faces a $1,000 immediate funding gap even though the cash has not disappeared from the balance sheet. The top-up is additional collateral, not automatically another $5,000 trading loss.
That extension changes the question from “What is the portfolio worth?” to “Can it meet this obligation at this time?” If collateral is moved from another account, identify the transfer route and deadline. If an asset must be sold, apply the stressed execution cost and settlement timing. If a hedge is closed to raise cash, recalculate the remaining portfolio’s exposure. A proposed rescue cannot be treated as both instantly available and free of consequences.
Then look through the holdings. If both fictional equity baskets own some of the same companies, their combined company exposure is the sum of the indirect holdings. If the crypto and FX positions depend on the same platform or banking channel, that shared operational dependency is not captured by price correlation. These checks do not establish that the assets always move together; they identify channels through which one event could impair several parts of the plan.
The reduced-exposure portfolio passes Omar’s stated 10% loss threshold in the original scenario, but that is only one test. A complete comparison would retain the original price shock, the deeper crypto-loss exercise and a separate cash-access scenario, with consistent starting values and cost conventions. Report where each construction helps and where it does not. This prevents a favorable result in one chosen scenario from becoming a blanket claim that the portfolio is diversified or safe.
Where the reasoning goes wrong
Counting tickers instead of drivers
Several holdings may depend on the same financing conditions or investor appetite.
Ignoring equity versus notional
A leveraged sleeve’s allocated equity is not its underlying market exposure.
Assuming all liquidity is immediate
A marketable asset may still fail to produce transferable cash before a margin deadline.
Test the decision, not your memory.
Keep the original positions but change the crypto loss from 25% to 40%. Leave the other shocks unchanged and use 0.75% costs on stressed risky liquidation value. What is the total portfolio loss?
Show the worked answer
Crypto loses $4,000 instead of $2,500. Price losses total $8,300. Risky assets are worth $40,000 − $8,300 = $31,700, and exit costs are $237.75. Total loss is $8,537.75, equal to 17.0755% of $50,000. Ending value is $41,462.25.